The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Used boat finance in Australia can involve extra checks compared with buying new, especially when purchasing from a private seller. Understanding PPSR searches, ownership documents, encumbrances, insurance and lender settlement steps can help you prepare before applying.
Financing a used boat or buying through a private sale in Australia can be more involved than purchasing a new vessel from a dealer. The lender may need to confirm the boat's identity, condition, value, ownership details and whether another lender or finance provider already has a registered interest in it.
This guide explains how used boat finance in Australia commonly works, what changes when the seller is private, and what checks buyers can consider before signing a contract or transferring money. It is general information only and does not take into account your objectives, financial situation or needs.
How used boat finance in Australia usually works
Boat finance can be arranged in different ways, depending on the lender, the borrower and the vessel being purchased. Many used boat purchases are financed with either a secured boat loan or an unsecured personal loan.
- Secured boat finance generally uses the boat as security for the loan. The lender will usually want to assess the boat's details, value, age, condition and ownership status before approving and settling the loan.
- Unsecured finance may not require the boat to be used as security, but eligibility, loan limits, interest rates and terms will depend on the lender's criteria and your personal circumstances.
If you are still comparing the broad finance pathways available, the Boat Loans Australia homepage outlines general boat loan finance options and can be a useful starting point before you move into the detail of a specific used boat purchase.
What changes when buying from a private seller?
A private sale boat finance transaction can require more coordination because there is no dealer handling the paperwork, invoice process and settlement administration. The buyer, seller, lender and sometimes a broker may need to work together to confirm the details needed for approval and payment.
With a private seller, the lender may ask for information such as the seller's identification, proof of ownership, registration papers, the boat's Hull Identification Number or serial details, a signed sale agreement, and bank account or payout details. If the boat is already under finance, the lender may also require a payout letter from the existing financier.
Private sales are not automatically riskier, but they can leave more responsibility with the buyer to complete due diligence. A lender's checks are not a substitute for your own inspection, mechanical review, documentation review or legal advice where appropriate.
Pre-approval can help before you choose a used boat
Some buyers seek pre-approval before making an offer on a used boat. Pre-approval can help you understand an indicative borrowing limit and likely repayment range, subject to the lender's final assessment and the specific boat meeting its criteria.
Pre-approval is not a guarantee that the final loan will be approved. A lender may still decline or change an offer after reviewing the vessel, the sale documents, your updated financial position, or any issue with the seller or existing finance. However, pre-approval can make it easier to shop within a realistic budget and respond more quickly when a suitable used boat becomes available.
Key checks before committing to used boat finance
Before you rely on finance to complete a used boat purchase, consider the following checks. The level of checking required may vary depending on the boat's value, age, complexity and where it is registered or stored.
Confirm the boat's identity
Make sure the boat details in the advertisement, sale agreement, registration documents and finance application match. This may include the make, model, year, engine details, trailer details, registration number, Hull Identification Number and any other serial numbers available.
Differences between documents do not always indicate a problem, but they should be explained before you proceed. Lenders may also query inconsistencies because they affect asset identification and security registration.
Complete a PPSR boat check where relevant
A PPSR boat check can help identify whether a registered security interest exists over the boat or related equipment. PPSR stands for the Personal Property Securities Register, a national register used for security interests in personal property.
A PPSR search may be relevant where a boat, engine or trailer has identifying serial details. It may show whether another lender or finance provider has a registered interest. If there is an existing interest, this does not necessarily mean the sale cannot proceed, but it does mean settlement needs to be handled carefully so the existing finance is paid out and the security interest can be released.
A PPSR search is not the same as a full condition report, ownership guarantee or legal review. It may not reveal every practical issue with a boat, and the accuracy of the search depends on using the correct identifying details.
Check registration and ownership paperwork
Boat registration rules and documentation requirements vary between Australian states and territories. A registration certificate may help confirm details about the vessel, but it should not be treated as complete proof that the boat is free from finance or other claims.
Ask the seller for available registration papers, proof of purchase, service records, receipts for major work, engine documentation and trailer paperwork if a trailer is included. Check that the seller's details are consistent with the person or entity selling the boat.
Inspect the boat and consider a professional assessment
Used boats can vary significantly in condition, even when they appear similar online. Depending on the vessel, it may be sensible to arrange an inspection, mechanical check, survey or sea trial before finalising finance. This is separate from the lender's assessment and is about understanding whether the boat is suitable for your intended use and budget.
Existing content on avoiding used boat buying mistakes can help with condition-related checks, while this article focuses on the finance and settlement process.
Documents commonly needed for used boat finance
Documentation requirements differ between lenders and loan types. The following table summarises common examples, but you should confirm the exact requirements with the lender, broker or finance provider assessing your application.
| Document type | Why it may be requested |
|---|
| Buyer identification and income documents | To verify your identity, income, employment, affordability and credit profile. |
| Sale agreement or tax invoice | To confirm the agreed purchase price, seller details and boat being financed. |
| Boat registration and serial details | To identify the vessel, engine and trailer and confirm they match the application. |
| PPSR search or security interest details | To identify whether another party has a registered security interest. |
| Existing finance payout letter | To show the amount needed to clear the seller's current loan, where applicable. |
| Insurance confirmation | Some lenders may require suitable insurance before or at settlement when the boat is used as security. |
| Valuation, inspection or survey report | To support the lender's assessment of the asset or help the buyer assess condition. |
For a broader preparation list, see What Documents Do You Need for a Boat Loan in Australia?. That guide covers general borrower and application documents, while this article explains the private-sale and used-boat settlement issues in more detail.
Don't forget the insurance!
 Insurance Online is an Australian online insurance resource with articles, guides, calculators and news on personal and business cover. Enquiries are referred to licensed brokers from a national partner network who can discuss your needs and compare options.
What happens if the used boat already has finance owing?
It is common for vehicles and recreational assets to have finance owing when they are sold. The important point is that the existing loan needs to be paid out and any registered security interest should be released as part of settlement.
If a PPSR search shows an encumbrance or the seller tells you there is finance owing, ask for current payout details from the existing financier. The payout figure may have an expiry date because interest and fees can change the amount owing over time.
In a financed purchase, the new lender may pay the existing financier directly, then pay any remaining sale proceeds to the seller. This reduces the risk of funds being paid to the seller while a previous security interest remains unresolved. The exact process depends on the lender, the existing financier and the transaction details.
If you are paying a deposit before settlement, be cautious about how much you pay, what happens if finance is not approved, and whether the sale agreement clearly records refund conditions. Consider getting independent advice if the contract terms are unclear.
How lender settlement may work in a private sale
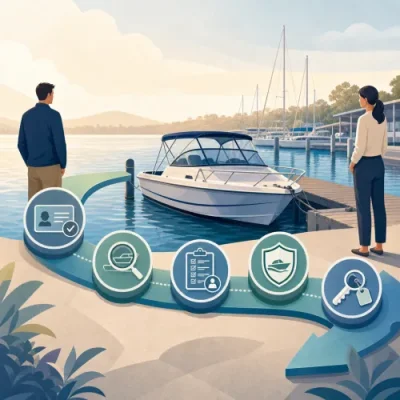
Settlement is the step where loan funds are paid and ownership transfer can proceed. In a private sale, the process may include:
- Application and conditional approval: You provide personal, financial and purchase details. Any approval may remain conditional until the lender checks the boat and documents.
- Asset and seller verification: The lender reviews the boat details, seller documents, PPSR or encumbrance information, and any insurance requirements.
- Loan contract review and signing: You review the loan contract, including repayments, interest rate, fees, term, security terms and your obligations.
- Settlement instructions: The lender confirms who must be paid, such as the existing financier, private seller or both.
- Funds released: The lender pays according to its settlement process. Timing can vary and may be affected by document accuracy and third-party response times.
- Transfer and post-settlement tasks: The buyer and seller complete registration transfer, handover and any lender-required follow-up documents.
A finance broker may help coordinate information between the buyer, seller and lender, particularly where there is an existing payout, multiple assets such as a boat and trailer, or uncertainty about the documents required. You can learn more about available assistance through the Brokers page.
Estimating repayments on a used boat purchase
Before making an offer, it is worth estimating how the purchase price, deposit, loan amount, interest rate and loan term could affect repayments. A used boat may also involve extra upfront or near-term costs such as inspection fees, registration transfer, insurance, safety equipment, servicing, storage, trailer repairs or upgrades.
You can use a boat loan calculator to test different loan amounts and repayment scenarios. Calculator results are estimates only and do not confirm approval, rates, fees or final repayment amounts. Actual loan terms depend on lender criteria, the loan product, the boat, your credit profile and your broader financial position.
Used boat finance risks to watch for
Financing a used boat can be practical, but there are risks to manage before you commit.
- Overpaying for the vessel: A lender may assess whether the boat's value supports the requested loan, but you should still compare similar boats and consider condition.
- Unresolved encumbrances: If existing finance is not properly paid out, a registered security interest may remain an issue after purchase.
- Incomplete seller documents: Missing registration, ownership or serial details can delay approval and settlement.
- Condition problems: Finance approval does not mean the boat is mechanically sound or suitable for your intended use.
- Insurance delays: If the lender requires insurance before settlement, waiting until the last minute can delay payment.
- Deposit disputes: A private-sale agreement should clearly explain what happens if finance is declined or conditions are not met.
Questions to ask before financing a used or private-sale boat
Before applying for private sale boat finance or signing a sale agreement, consider asking:
- Is the seller the registered owner or otherwise authorised to sell the boat?
- Do the boat, engine and trailer serial details match the documents?
- Has a PPSR search been completed using the correct identifying details?
- Is there finance owing, and if so, who will pay the existing financier at settlement?
- Will the lender require a valuation, survey, inspection or insurance certificate?
- Are the deposit and refund conditions clear if finance is not approved?
- Are ongoing costs such as insurance, storage, maintenance, fuel and registration affordable within your budget?
- Does the loan contract allow repayment flexibility, early repayment or other features you value, and are there fees for using them?
Final thoughts
Financing a used boat or private sale in Australia is often achievable, but it usually requires careful coordination of boat details, seller documents, PPSR checks, insurance and settlement instructions. The main difference from a dealer purchase is that the buyer may need to take a more active role in confirming the boat's identity, ownership position and existing finance status.
Before committing, make sure you understand both the loan and the vessel. Compare finance options, check the paperwork carefully, allow time for settlement, and seek professional help where the transaction is complex or the risks are unclear.
Published: Saturday, 8th Aug 2026
Author: Paige Estritori


I nearly missed the PPSR boat check on a private sale, so the payout letter point is worth spelling out before handing over a deposit.